Gold Posts Its Strongest Week Since January as Rate Expectations Ease
Gold rose more than 6% in its strongest week since January as softer economic data reduced expectations for an imminent Federal Reserve rate increase.
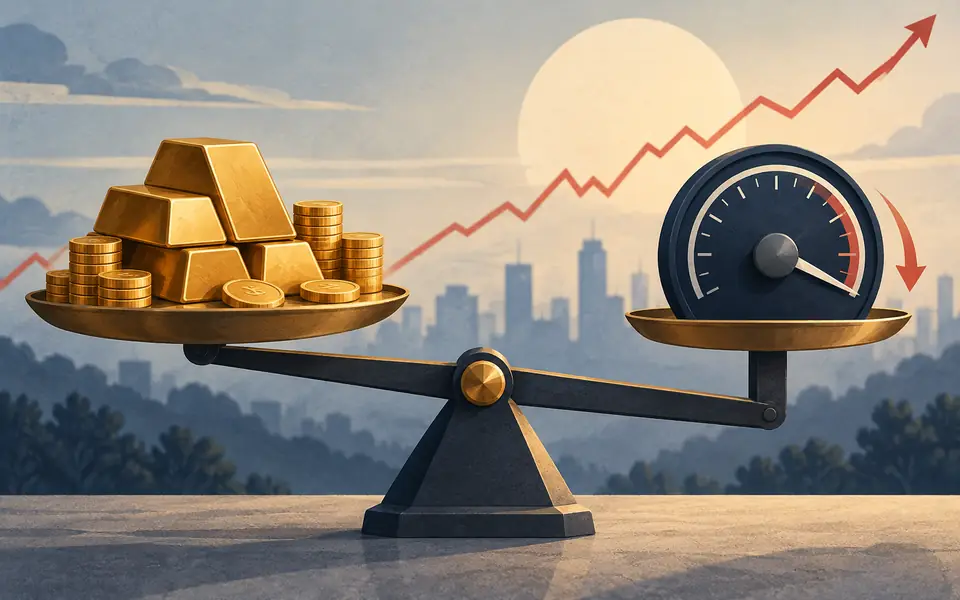
Gold rose more than 6% in its strongest week since January as softer economic data reduced expectations for an imminent Federal Reserve rate increase. The move followed a volatile stretch for precious metals and does not remove the sensitivity of gold prices to inflation data, the dollar and changes in real interest rates.
To understand why this rebound matters, it helps to look at how rough 2026 has actually been for gold traders trying to time the market. The metal roared into the year by smashing through a series of records, eventually topping $5,300 an ounce, only to spend much of the following months grinding lower as the initial wave of safe-haven buying cooled off. For a trade that looked like a one-way bet in January, the reversal caught plenty of investors off guard.
What changed rate expectations
Two things did the heavy lifting behind this month's bounce: softer-than-expected inflation data and a noticeable cooling in expectations that the Federal Reserve might need to raise interest rates. Gold doesn't pay a dividend or interest, so it tends to struggle when rates are high or climbing, since investors can earn a safe return elsewhere instead. When the odds of a rate hike fade, gold typically gets more attractive by comparison, and that's roughly what played out this time.
Analysts caution the recovery doesn't erase the bigger picture of a choppy year. Short-term volatility in the gold trade is likely to persist, and the metal's path for the rest of 2026 will probably keep swinging with every fresh inflation print and every shift in how traders read the Fed's next move, rather than settling into the kind of steady climb that defined 2025.
The wider context for gold prices
Zoom out further and gold's 2026 makes a lot more sense as a hangover from an extraordinary run. The metal gained roughly 65% in 2025, outperforming nearly every major asset class except silver and the platinum group metals, fueled by a combination of central bank buying, ETF inflows, and investors hedging against currency and geopolitical risk. Global gold ETF holdings swelled to a record 4,025 tonnes last year, while annual inflows into gold-backed funds hit an all-time high of $89 billion.
Central banks have been one of the quieter but more persistent forces behind the entire multi-year rally. China's central bank alone extended its gold-buying streak well past a year, and demand from emerging-market monetary authorities has stayed elevated as more countries look to diversify their reserves away from a heavy reliance on the US dollar. That kind of structural buying doesn't disappear overnight just because prices pull back for a few months.
Forecasts and their limits
Even after the recent stumble, big banks haven't abandoned their bullish calls. Major brokerages surveyed earlier this year had penciled in $5,000 an ounce as a realistic target for 2026, pointing to expectations of lower US real interest rates, continued Fed easing over time, and ongoing central bank diversification as reasons the longer-term trend should stay intact even if the ride there is bumpier than expected.
For everyday investors, the takeaway from this stretch is less about picking the exact top or bottom and more about recognizing gold's role as a hedge that moves on its own logic, often at odds with stocks and bonds. This month's rebound is a reminder that even after a sharp pullback, the underlying demand drivers — central banks, geopolitical uncertainty, and rate expectations — haven't gone anywhere, they just needed a fresh trigger to reassert themselves.
Sources and further reading: Kitco weekly gold market report
About the Author
Elena Vasquez
Finance Writer
Elena Vasquez writes about markets, interest rates, household finance, and economic data. She tracks Federal Reserve policy, inflation reports, and how monetary decisions filter down to borrowing costs and household budgets. Her posts separate observed figures from forecasts and interpretation, citing primary data releases wherever they're available.